
Blackpool house prices rise nearly £2.5K in a year
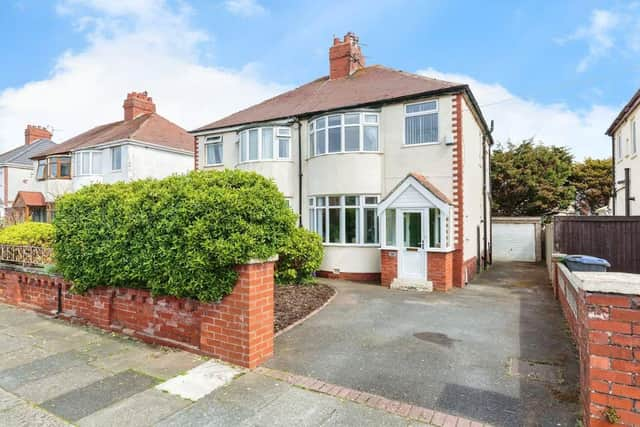
Homeowners across Blackpool have seen nearly £2,500 added on to the value of their property - amid a UK-wide boom in house prices.
UK property values increased 3.9% year-on-year in this week's House Price Index, worth an additional £10,000 on average.
Those who own property in Blackpool were below the average from May 2024 to May this year, with an increase of £2,449 but more than £7,000 better off than neighbouring Lancaster where property dropped by over £5,000 in the last 12 months.
This means house prices in Blackpool are now £128,930, lower than the UK average.
The average UK home is now worth £269,000 following the 3.9% rise over the last 12 months which added £10,000 to prices.
House prices in England saw an annual price rise of 3.4%, making the average property worth £290,000, while Wales had a 5.1% increase and homes stood at £210,000 on average.
North of the border in Scotland there was no monthly increase but an annual 6.4% rise, meaning the average Scottish home now costs around £192,000.
The report revealed more than 80,000 properties were sold in March 2025 surpassing the totals from both 2023 and 2024.
Tom Evans, sales director at Purplebricks Estate Agency said: “Great news once again for the nation’s homeowners, and at a promising time for first-time buyers too.
“The falling interest rates over the last 12 months has helped drive down mortgage rates and drive up property prices - and the forecast base rate cut in August should continue that trend.
“We are confident house prices will continue to rise into next year, meaning your home at the start of 2026 will be worth more than it is today.”
Robert Nichols, managing director of Purplebricks Mortgages said: “This is the best time to be a first-time buyer in recent years.
“Lower interest rates, means lower mortgage rates. And, while that is pushing up house prices, it also acts as a confidence booster to would-be buyers that owning property pays dividends.
“And, the government’s new ‘Helping Hand’ scheme for first-time buyers - making more mortgages available at 4.5 times a buyer’s income - will drive more movement in the market.”